
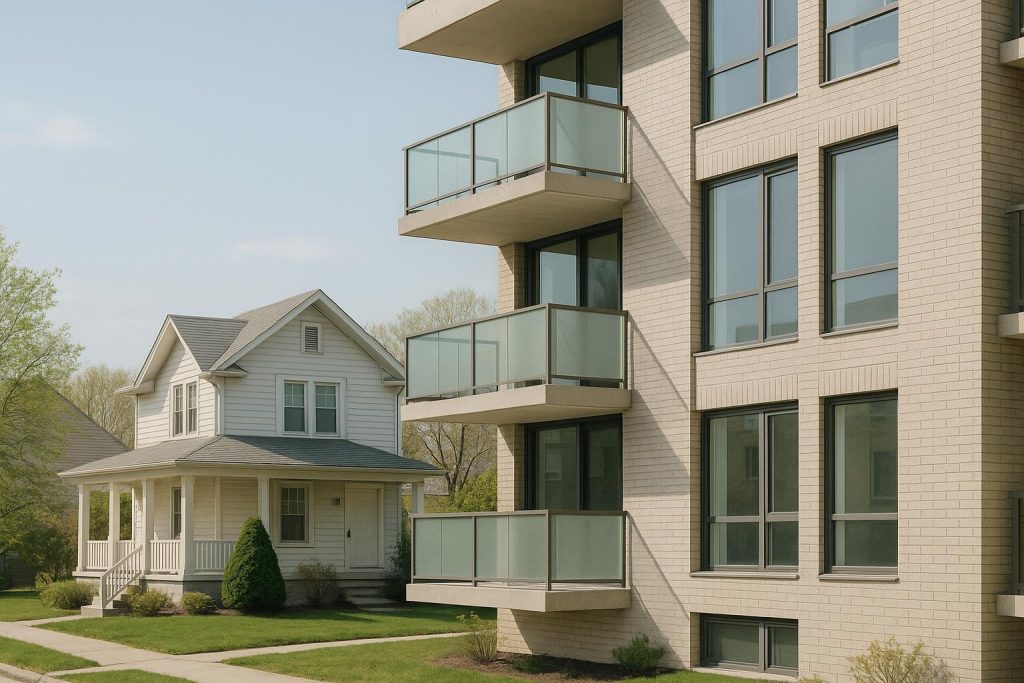
Real Estate Investment Strategies: Comparing Condos and Single-Family Homes
When it comes to securing steady returns through real estate, new and experienced investors alike often wrestle with a central question: is it better to put capital into individual condos or single-family homes? Both pathways offer unique advantages, and neither is a universal solution for every investor. In reality, the most suitable choice depends on multiple factors, from your available budget to your personal risk tolerance and your aspirations for long-term property management. This comprehensive guide explores the pros and cons of each property type, as well as their typical return dynamics, helping you make informed decisions about your portfolio.
Location Matters for Both Condos and Single-Family Homes
No matter the property type, your chosen location has a considerable impact on both rental demand and resale potential. Look for well-connected neighbourhoods that feature job growth, access to public transit, a variety of amenities, and a healthy local economy. In many cases, high-growth areas with local shopping, restaurants, and recreational facilities attract consistent tenants and higher occupancy rates. Investors who conduct thorough area research and pay close attention to city planning initiatives often position themselves for more reliable returns.
Some communities may favor condos due to population density and a robust urban lifestyle culture, while others might feature a thriving market for single-family homes, particularly in quieter suburbs where families seek more space or proximity to schools. By examining future development plans, transportation upgrades, and local demographic shifts, you can gain a realistic sense of which asset–a condo or a house–would yield the best long-term value in a particular market.
Understanding Condos as an Investment Option
Lower Initial Investment: When compared to single-family homes in the same area, condos often present a lower barrier to entry because the purchase price can be more attainable for many first-time investors. This can be an advantage if you’re looking to start small, learn how to manage a rental, and gradually scale up.
Shared Maintenance and Amenities: Another feature that draws certain investors to condos is the shared maintenance responsibility. Owners typically pay a monthly homeowner association (HOA) or strata fee, which covers common area upkeep, landscaping, and sometimes exterior building repairs. Although this leads to recurring costs, it can simplify property management, especially for those who don’t want to worry about tasks like lawn care or external structure maintenance. Additionally, many condo buildings have amenities–such as a fitness center or common lounges–that appeal to a broad range of tenants.
Predictable Budgeting: Because maintenance is taken care of through a structured, regular fee, budgeting for expected expenses can be easier. You’ll often have fewer abrupt costs, such as a roof replacement or driveway repair, although there is always the possibility of special assessments if the condo association votes on major repairs. Even so, for many investors, the convenience of this predictable expense outweighs the risk of sudden repairs.
Urban Living Appeal: In bustling city centers, condos frequently attract young professionals, students, and downsizers seeking convenience and proximity to work or cultural attractions. This tenant pool values quick access to transportation, restaurants, and entertainment, making well-located condo units a strong contender in rental markets where urban living is a priority.
Potential Drawbacks: Despite the reduced maintenance workload, monthly HOA fees can add up substantially over time. Also, owners have less autonomy when it comes to making changes to the property’s exterior. The association’s regulations can limit how you use or modify the space. Additionally, condo boards set community standards and budgets, so if the building’s overall finances or management practices are poor, this may negatively affect the property’s value.
Exploring the Advantages of Single-Family Homes
Autonomy and Control: One of the most common reasons people choose single-family homes for investing is the enhanced feeling of control over the property. Unlike a condo, you are the sole decision-maker regarding landscaping, exterior improvements, and the home’s overall aesthetics, so you can implement certain renovations or expansions if your finances and local regulations permit. This autonomy can help you tailor the property to specific tenant needs or local market demands.
Appeal to Long-Term Renters: Single-family homes are often favored by families and tenants who prefer more privacy, a dedicated yard, and a stronger sense of independence. These renters may be more inclined to stay long term, thus reducing vacancy periods. Moreover, if the home is near good schools, parks, and essential amenities, families are likely to pay a premium for the location and commit to multi-year leases.
Land Appreciation: Since you own both the structure and the land, land appreciation can play a significant role in your investment profit. Over time, land in desirable regions tends to gain value, which can bolster your overall equity if you choose to sell. This factor differs from condos, as condo owners typically share the land with other unit owners. Land appreciation can be beneficial if you anticipate selling years down the road, especially in localities marked by population growth and limited land availability.
Potential Downsides: A single-family home requires complete attention to maintenance and repair. Everything from fixing the roof to ensuring the landscaping remains tidy can be your responsibility (unless you hire a property manager). Additionally, single-family homes generally require a higher initial investment, which might not align with every investor’s financial situation. If your budget is tight or you’d prefer placing less capital in a single property, condos may be a more appealing direction.
Comparing Maintenance Responsibilities
Maintenance obligations diverge significantly between condos and single-family homes. In a condo, the building’s governing association may cover the roof, exterior walls, shared piping, and communal areas. In contrast, single-family homeowners must handle these responsibilities on their own, which can mean a more hands-on approach or the need to contract property management professionals. While condo fees could appear burdensome, they can be less intimidating than facing a large roofing or foundation bill on your own. Ultimately, whether you view an HOA fee as an irritant or a convenience depends on your personal investment strategy and lifestyle preferences.
For individuals who wish to remain mostly hands-off, a condo or a single-family building with a dedicated property manager can simplify day-to-day obligations. Some investors enjoy the stewardship element that comes with owning a standalone home, while others find the stress of ongoing repairs detracts from an otherwise profitable venture. Understanding your own capacity for maintenance and your available free time can help guide you toward the right property type that supports your investment goals.
Assessing Return Potential and Risk Factors
Rental Yields: Examining current and projected rental yields in your target area is essential. If condos are commanding high rental demand due to their central location and proximity to workplaces, you might enjoy excellent monthly returns relative to your initial investment. However, HOAs can eat into these profits, so factor them into your cash-flow calculations.
With single-family homes, particularly those in family-friendly areas, rental yields may be slightly slower in certain markets but can prove more stable over longer tenancies. Families might opt to remain in the same home for multiple years, providing you with consistent income. It’s crucial to analyze typical occupancy rates and rent prices in similar homes close by before purchasing.
Market Volatility: Real estate values can fluctuate in response to economic cycles. In some cases, condos may experience more pronounced price swings if the local condo market experiences overbuilding or shifting buyer preferences. Single-family homes often have broader buyer demand, but they can still be impacted by sudden dips in the local economy. Diversifying across property types–or even across different cities–can help mitigate the risk of market-specific downturns.
Liquidity: Condos in prime locations often sell fairly quickly, as they attract both end-users and investors. Houses in suburban or rural areas might remain on the market longer, depending on local demand. Keep in mind that liquidity can affect your decision if you anticipate selling on a shorter timeline or need fast access to capital.
Diversifying Your Real Estate Portfolio
Many seasoned investors eventually acquire a mix of property types to spread out risk and capitalize on multiple market segments. For instance, a portfolio that includes both condos and single-family homes might balance the steady occupancy rates and potential land appreciation of single-family residences with the typically lower purchase price and convenience of condos.
When diversifying, it’s important to maintain a coherent strategy that aligns with your financial capacity, personal interest level in property management, and your broader market knowledge. Continuously monitor each property’s performance and re-evaluate whether it still fits your objectives. Sometimes, local trends or personal life changes may alter your priorities, prompting you to invest in a new type of property or sell one that no longer aligns with your vision.
Tips for Successful Investing in Both Property Types
- Perform Comprehensive Market Research: Always investigate local area statistics, market rent averages, potential condominium developments, or single-family new construction plans before making a purchase.
- Agent and Lender Partnerships: Collaborate with professionals who understand your chosen market and can direct you toward properties that fit your risk tolerance and prospective ROI.
- Plan for Contingencies: Whether investing in a condo or a house, keep a cushion for unexpected expenses, such as vacancy periods or urgent repairs that go beyond routine maintenance.
- Stay Attuned to Wider Real Estate Trends: Even if you operate locally, national or global economic conditions–like interest rate changes–can affect your property’s value or your ability to refinance.
- Leverage Professional Management (if Needed): Hiring a property management company, especially for single-family homes, can provide a layer of oversight, ensure that mortgage and utility payments are handled, and free up your time to focus on other aspects of your portfolio.
Future Outlook and Long-Term Considerations
When deciding between condos and single-family homes, it’s helpful to consider neighborhood development plans. You may uncover future public infrastructure upgrades, local business expansions, or new housing projects that could shift the desirability of certain areas. For condos, keep an eye on the number of new units being built, as excessive supply can temporarily push prices and rents downward. For single-family homes, watch out for major zoning changes or development trends that might influence the character and density of a neighborhood.
Beyond external factors, stay aware of broader market conditions like interest rates, lending policies, and government incentives for rental housing. If you’re looking at properties in dynamic urban areas, you may find greater opportunities for condo appreciation. Meanwhile, suburban or exurban regions–where single-family homes have historically thrived–can sometimes offer a stable, long-term tenant base that’s eager to stay rooted in the same area for multiple years.
Aligning Your Choice with Personal Goals
Ultimately, the investment you choose should align with your lifestyle, financial position, and vision for the future. If your career or personal commitments leave little time for hands-on property management, a lower-maintenance condo could be ideal. On the other hand, if you’re passionate about home improvements or want to customize a property over time, a single-family residence might be more fulfilling. You might also consider whether you plan to live in the property later. Some people buy a condo in a central location, renting it out in the short term and eventually moving in themselves when it suits their personal or professional circumstances. Similarly, a single-family home can become your long-term residence once you’re ready to exit the landlord phase.
Leaning on Professional Insights
If you feel uncertain about where to begin, enlist the support of real estate advisors with expertise in both condominiums and single-family properties. Their knowledge can help you comprehend local bylaws, rental demand, pricing trends, and any building-specific regulations. In many cases, real estate professionals are also aware of off-market deals or up-and-coming developments that may fit your portfolio goals.
Furthermore, if you wish to explore emerging properties or sustainable multi-family projects, there are numerous new developments gaining popularity among environmentally conscious tenants. Some investors discover intriguing opportunities by looking for projects that emphasize responsible development, community connectivity, and modern design philosophies. You can find inspirational examples of such initiatives through our Projects page, where purpose-built communities reflect thoughtful planning and quality.
Making the Final Decision
When you try to determine whether a condo or a single-family home is the better option, remember that there isn’t always a cut-and-dried answer. Both have the potential to generate steady returns, provided you understand the nuances involved and perform robust due diligence. Condos can be more approachable, especially for newer investors looking for manageable maintenance responsibilities. Single-family homes, on the other hand, can deliver a sense of autonomy and typically accrue added land value over time.
The decision rests on knowing the characteristics of your target market, crunching the numbers accurately, and envisioning how each property type fits into your personal investment objectives. Many investors find success in diversifying across both markets, capturing the unique benefits that condos and single-family homes can offer. Regardless of direction, the key principles remain consistent: research thoroughly, plan your finances realistically, and stay aware of shifting market conditions. By approaching your strategy with clear goals and flexibility, you increase the likelihood of enjoying steady returns and the long-term appreciation you’re aiming for in real estate.
When you’re ready to move forward, reflect on the type of ownership experience you prefer, the potential cost structure of each property category, and the local rental market’s proven track record. With careful investigation, a well-thought-out financial plan, and ongoing commitment, you can create a real estate portfolio that stands on a firm foundation, whether that means condos, single-family homes, or a combination of both.
